September 2026. Research note. Sample figures throughout.
The Two Slabs
0.0CPR faster, Ginnie against Fannie, sample month
Ginnie against Fannie at the same coupon: three sources of the speed gap, each measurable from the disclosure files alone.
Reading time line: About 5 minutes.Sample figures throughout
Put a Ginnie Mae pool and a Fannie Mae pool side by side at the same coupon and the first thing a new analyst notices is that the coupons match. The second thing, a few prints later, is that nothing else does. In the sample month on this site, Ginnie speeds ran 2.1 CPR faster than Fannie at the same coupon. CPR is how fast borrowers prepay, annualised, and 2.1 of it is a real difference on a bond you paid a payup for. The gap is not a mystery. It has three sources, and each one leaves a mark in the public files.
Same coupon, different borrower
ScoreCredit scores run lower.
LTVLoan to value ratios run higher, often above 95 percent at origination for FHA.
BalanceBalances run smaller.
Down paymentDown payments are thinner, so the equity cushion that lets a conventional borrower take cash out is thinner too.
A Fannie pool is made of conventional loans. A Ginnie pool is made of government insured loans, mostly FHA and VA, with a smaller share from USDA. Those programmes exist to lend to borrowers the conventional market prices out, so the borrower base differs on every field the disclosure file carries. Credit scores run lower. Loan to value ratios run higher, often above 95 percent at origination for FHA. Balances run smaller. Down payments are thinner, so the equity cushion that lets a conventional borrower take cash out is thinner too.
Each of those cuts a different way. A lower score and a higher LTV make a rate and term refinance harder to qualify for in the conventional market, which slows things down. A smaller balance means less dollar saving per refinance, which slows things down again. So on the borrower base alone you might expect Ginnie to be slower. It often is not, which is where the other two sources come in.
The servicer is part of the speed
A Ginnie servicer may purchase a loan out of the pool once it is 90 days delinquent. To the investor in the pool that purchase looks exactly like a prepayment: the balance leaves the pool at par. So Ginnie speeds carry an involuntary component that has nothing to do with rates and everything to do with credit and with servicer behaviour. When delinquencies rise, those purchases rise with them, and a Ginnie pool can print fast in a month when nobody refinanced anything.
The servicer's identity matters on the voluntary side as well. Ginnie servicing is concentrated in nonbank servicers, and a nonbank servicer that also originates has every reason to recapture its own borrowers when rates move. The disclosure file names the servicer on every pool. It is one of the most informative columns in it and one of the least used.
On the servicer column
It is one of the most informative columns in it and one of the least used.
The refinance channel
Two squared stacks, one taller. Sample photograph.
The third source is the channel a government borrower refinances through. The FHA Streamline and the VA Interest Rate Reduction Refinance Loan need no new appraisal and limited re-underwriting, so the frictions that slow a conventional borrower with a high LTV or a thin file are mostly absent. There are seasoning rules, but once they are met a government borrower who is in the money can be moved quickly and at scale by a servicer that wants the business. That is why Ginnie speeds can outrun Fannie speeds in a rally even though the Ginnie borrower base looks slower on paper.
So the honest summary of the three sources is: the borrower base pulls one way, the delinquent purchase channel and the streamline channel pull the other, and which wins depends on rates and on credit conditions in the month you are looking at. A 2.1 CPR gap is the net of three forces, not a property of Ginnie.
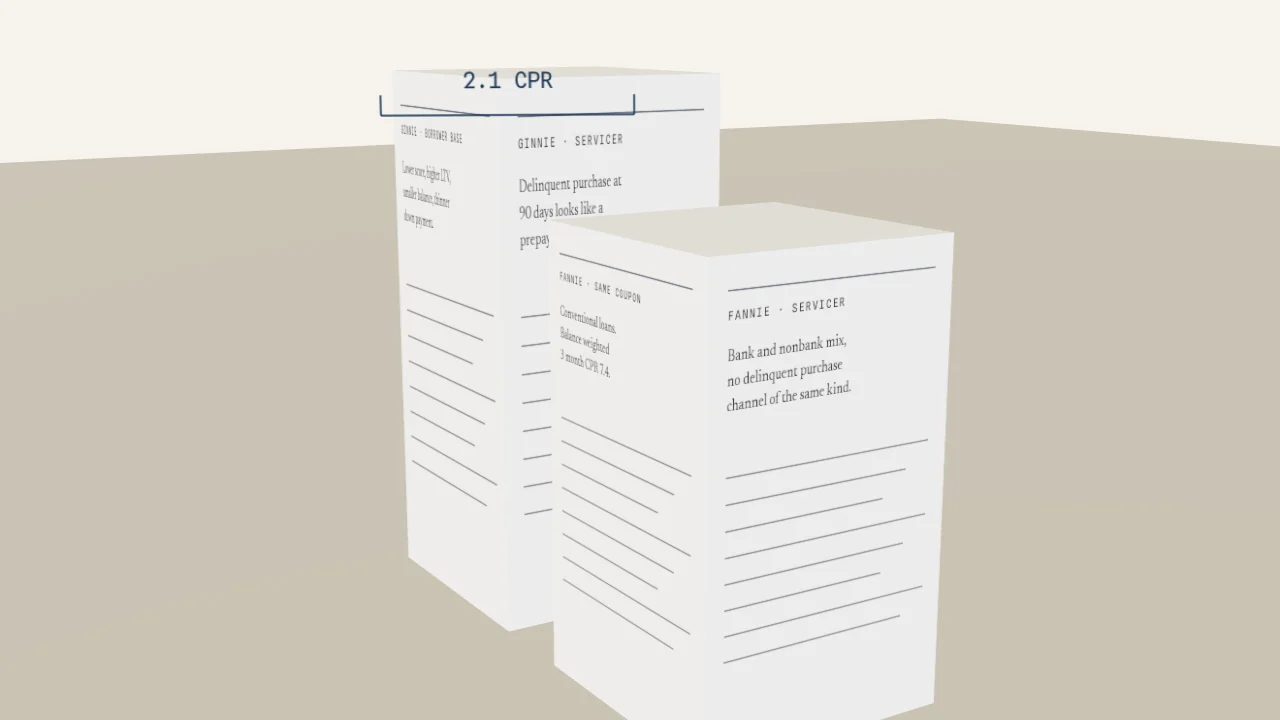
Two slabs at the same coupon. Each swing reveals the next source.
Ginnie · borrower base
Servicer
Refinance channel
Fannie · same coupon
Servicer
Channel
Building the comparison from disclosure data alone
None of this needs a vendor model. It needs the two agencies' month end loan-level files and a consistent recipe.
Two slabs, three labelled faces, the 2.1 CPR bracket.
01Pull both agencies' files for the same month, and keep the file name, the row count and the timestamp.
02Define the cohort the same way on both sides: coupon, production year, and a seasoning band. Same coupon is not the same note rate, and the gap between coupon and note rate differs by agency, so record the weighted average coupon of each side as well.
03Compute each pool's monthly prepayment from the factor change after scheduled amortisation, annualise it to CPR, and weight by balance, never by pool count.
04Split the Ginnie side into voluntary and involuntary where the file supports it, so a month of delinquent loan purchases is not mistaken for a month of refinancing.
05Difference the two balance weighted series, month by month, for at least six prints. One month of gap is noise for all the reasons covered in the note on six prints.
06Keep the servicer column. If the gap is concentrated in two servicers, you have learned something about two servicers, not about Ginnie.
Every number that comes out of that recipe has a row behind it that anyone with the same files can find. That is the whole standard.
What 2.1 CPR is worth, and what it is not
A gap of 2.1 CPR between agencies at the same coupon is worth knowing before you compare payups across them, because a Fannie pool that prints 7.4 and a Ginnie pool that prints 7.4 are not equally slow relative to their own cohorts. It is worth knowing before you size a rate scenario, because the streamline channel changes the shape of the response as well as its level. What it is not is a rule. It is one month's net of three forces, and the sign has flipped in other months.
What would break it
A coupon match that hides a 30 bp difference in weighted average note rate is not a like for like comparison, and the gap you measure is partly the rate difference.
A wave of delinquent loan purchases in a weak credit month will show Ginnie running fast for reasons that reverse the moment the delinquent loans are gone.
A change to the streamline seasoning rules changes the channel overnight and every prior print with it.
And a cohort built on pool count instead of balance will be dragged by whichever side has more small pools.
The comparison breaks when the two sides stop being comparable. A coupon match that hides a 30 bp difference in weighted average note rate is not a like for like comparison, and the gap you measure is partly the rate difference. A wave of delinquent loan purchases in a weak credit month will show Ginnie running fast for reasons that reverse the moment the delinquent loans are gone. A change to the streamline seasoning rules changes the channel overnight and every prior print with it. And a cohort built on pool count instead of balance will be dragged by whichever side has more small pools.
Name those in the memo before you write the number. Then write the number.
Smart Augment publishes research. This note is not investment advice, and model output is an estimate.
Research outputs for the customer's own investment professionals. Not a recommendation, an offer or a solicitation. Models are estimates. Figures derive from official agency disclosures and public market data.
The cross agency line on the Desk screen is rebuilt every month from both files. See it on the How it works page.